Insurance for Independent Carpenters & Woodworkers
A cabinet door you hung swings into a client’s face, or a dining table you built collapses at a dinner party six months after delivery. Insurance for independent carpenters and woodworkers starts with general liability and tool coverage for on-site work, and woodworkers who sell furniture also need product liability for items that fail after the sale. The right mix depends on where you work and what you sell.
Need
Business Insurance ?
Get a Quote
A finish carpenter who works only in clients’ homes faces different claims than a furniture maker who works alone in a garage shop. Many tradespeople do both, so their policies have to cover both sets of risks.
Before you request quotes, write down three things: where you work, what equipment you own, and whether finished pieces leave your hands for someone else’s home.
On-Site Carpentry vs Shop Woodworking Risks
On-site carpenters work on property that belongs to someone else. Because of this, most claims involve damage to a client’s home or injuries to people who walk through the work area.
Typical on-site claims include:
- A dropped nail gun or a ladder that gouges hardwood floors or cracks tile
- A homeowner or visitor who trips over cords, offcuts, or open stair framing
- Water damage after a cut into a wall nicks a supply line
- Theft of tools from a truck parked overnight at the job
General liability is the core policy for these risks. It responds to third-party bodily injury and property damage. The work is similar to what handymen face, and our guide to handyman insurance coverage covers many of the same job-site scenarios. If you haul lumber and tools in a truck registered to your business, personal auto may not respond to a work-related accident, so compare commercial auto costs for tradespeople before you assume you are covered.
Shop woodworkers face fewer visitor injuries but more property risk. Fine dust, finishing solvents, and stored lumber increase fire exposure, and a single fire can destroy every machine and every unfinished commission in the building. Also, if your shop is in your garage, a homeowners policy often limits or excludes business property, which our article on home-based business insurance explains in more detail.
Product Liability for Furniture Makers
Product liability covers injuries or property damage caused by something you made after it leaves your control. For a furniture maker, that might be a chair leg that snaps, a bookshelf that tips onto a child, or a finish that stains a customer’s floor. In legal terms, a seller of a defective product can be held responsible even without proof of carelessness in some situations, as the overview of product liability law on Wikipedia describes.
Many general liability policies include “products-completed operations” coverage, but you should not assume it fits your work. Check these points with the insurer:
- Whether products-completed operations has its own aggregate limit, and how large it is
- Whether furniture you sell through craft fairs, online marketplaces, or consignment shops is covered
- Whether children’s furniture, cribs, or high chairs are excluded or rated differently
- Whether items you sell to customers in other states or countries are covered
Retailers and galleries often ask for a certificate naming them as additional insured before they stock your pieces. So when a store requests proof of coverage, confirm your policy allows that endorsement. To decide on limits, review how much liability coverage your clients and sales channels expect.
Protecting Tools and Shop Equipment
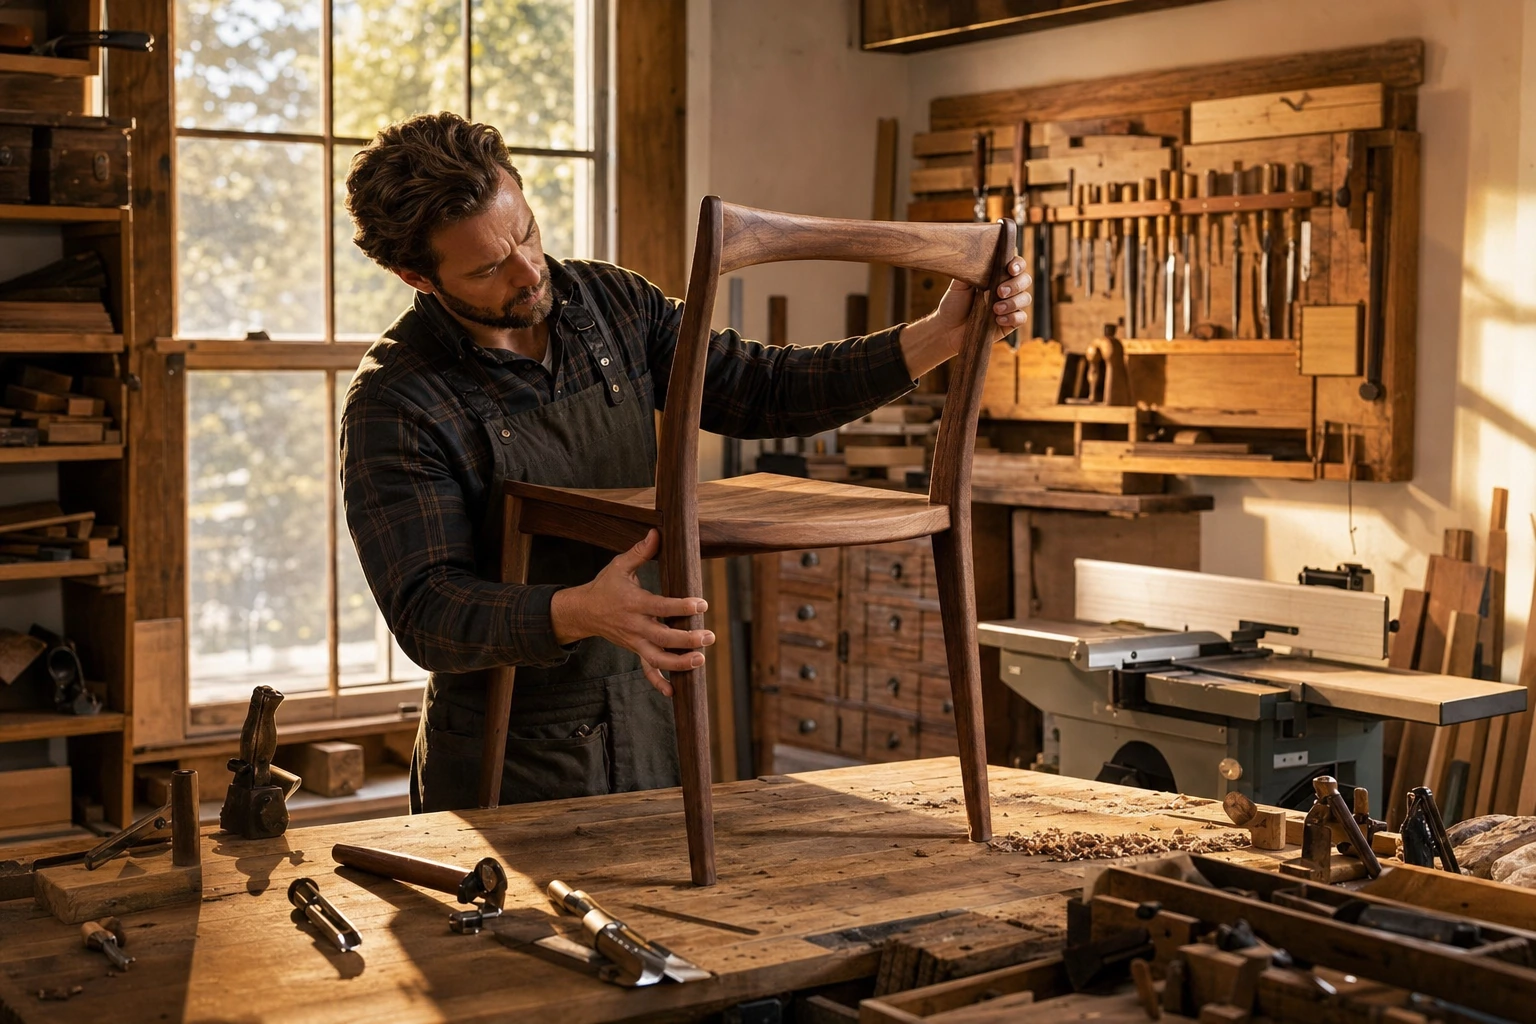
Tools are often the largest investment an independent carpenter owns, and general liability does not pay to replace them. You need separate property coverage, and the right type depends on where the equipment stays.
Portable tools that travel to jobs
Inland marine coverage, often sold as a “tools and equipment floater,” follows your circular saws, routers, and compressors to job sites and in your vehicle. Ask whether theft from an unattended vehicle is covered, since some policies require visible signs of forced entry.
Stationary shop machinery
Table saws, jointers, planers, and dust collection systems are usually insured as business personal property under a commercial property policy or business owner’s policy. Make sure the policy also covers materials and customer pieces in progress, because finished work that burns before delivery is a direct loss to you.
Use these steps to keep tool claims simple:
- Photograph every major tool and record its serial number.
- Keep receipts or replacement-cost estimates in cloud storage.
- Choose replacement cost rather than actual cash value, so older tools are not paid out at depreciated prices.
- Update the schedule each time you buy a significant machine.
Choosing Between BOP and Standalone Policies
A business owner’s policy (BOP) bundles general liability and commercial property, usually at a lower combined cost than buying each separately. Standalone policies cost more to assemble but let you tailor each piece. The table below compares the main options.
Get Your Business Insurance:
Get a Quote
| Option | Best fit | Main limitation |
|---|---|---|
| Business owner’s policy | Woodworkers with a shop and equipment to protect | Some insurers limit eligibility for woodworking because of fire risk |
| Standalone general liability | On-site carpenters who own few large machines | No coverage for your own tools or shop |
| General liability plus inland marine | Mobile carpenters with valuable portable tools | Two policies to manage and renew |
Bundling can lower costs, as the example of a sole proprietor bundling policies shows. Even so, a BOP rarely includes inland marine, workers’ compensation, or commercial auto, so you may still add those separately. If you hire a helper, read about workers’ comp for small contractors, because most states have rules for employers.
Frequently Asked Questions
Do independent carpenters need insurance if they work alone?
Most clients and general contractors will ask for proof of general liability before you start, even if you have no employees.
- A single damaged floor or injured visitor can lead to a claim larger than a year of premiums.
- Working alone may let you skip workers’ comp, depending on your state.
- Read about contractors working alone for a solo-focused checklist.
Does general liability cover furniture I sell?
Only if your policy includes products-completed operations coverage at a limit that fits your sales.
- Ask for the products-completed operations aggregate in writing.
- Confirm online and craft fair sales are included.
- Check for exclusions on children’s furniture.
Can I get coverage for a single job?
Some insurers offer short-term general liability for a defined project.
- This suits occasional carpenters with one contract.
- It will not cover products sold after the policy ends.
- See options for one-job liability insurance.
How should I compare carpenter insurance quotes?
Compare limits, deductibles, and exclusions side by side, not just the premium.
- Match each quote to the same liability limits.
- Check tool theft conditions and valuation method.
- Use this guide to compare business insurance quotes.
What does independent contractor insurance usually cost?
Costs vary by state, revenue, claims history, and whether you sell finished products.
Get Your Business Insurance:
Get a Quote
- Shop woodworking may be rated higher because of fire risk.
- Higher deductibles lower premiums but raise out-of-pocket costs.
- Review typical independent contractor insurance costs before budgeting.