How to Compare Small Business Insurance Quotes
Two quotes for the same general liability policy can differ significantly in price and still not be comparable, because the cheaper one may carry a lower aggregate, a higher deductible, or an exclusion that removes your main exposure. To compare small business insurance quotes accurately, put them side by side on identical limits, deductibles, exclusions, and policy forms, not just premium. Then check each insurer’s AM Best financial strength rating and claims reputation.
Need
Business Insurance ?
Get a Quote
A quote shows what you pay. The policy wording shows what you get.
The steps below work for contractors, plumbers, estheticians, dog walkers, retail shops, and fitness instructors. They apply whether you are pricing a single general liability policy or a full package that includes Commercial auto insurance and cyber coverage.
Line Up Limits and Deductibles
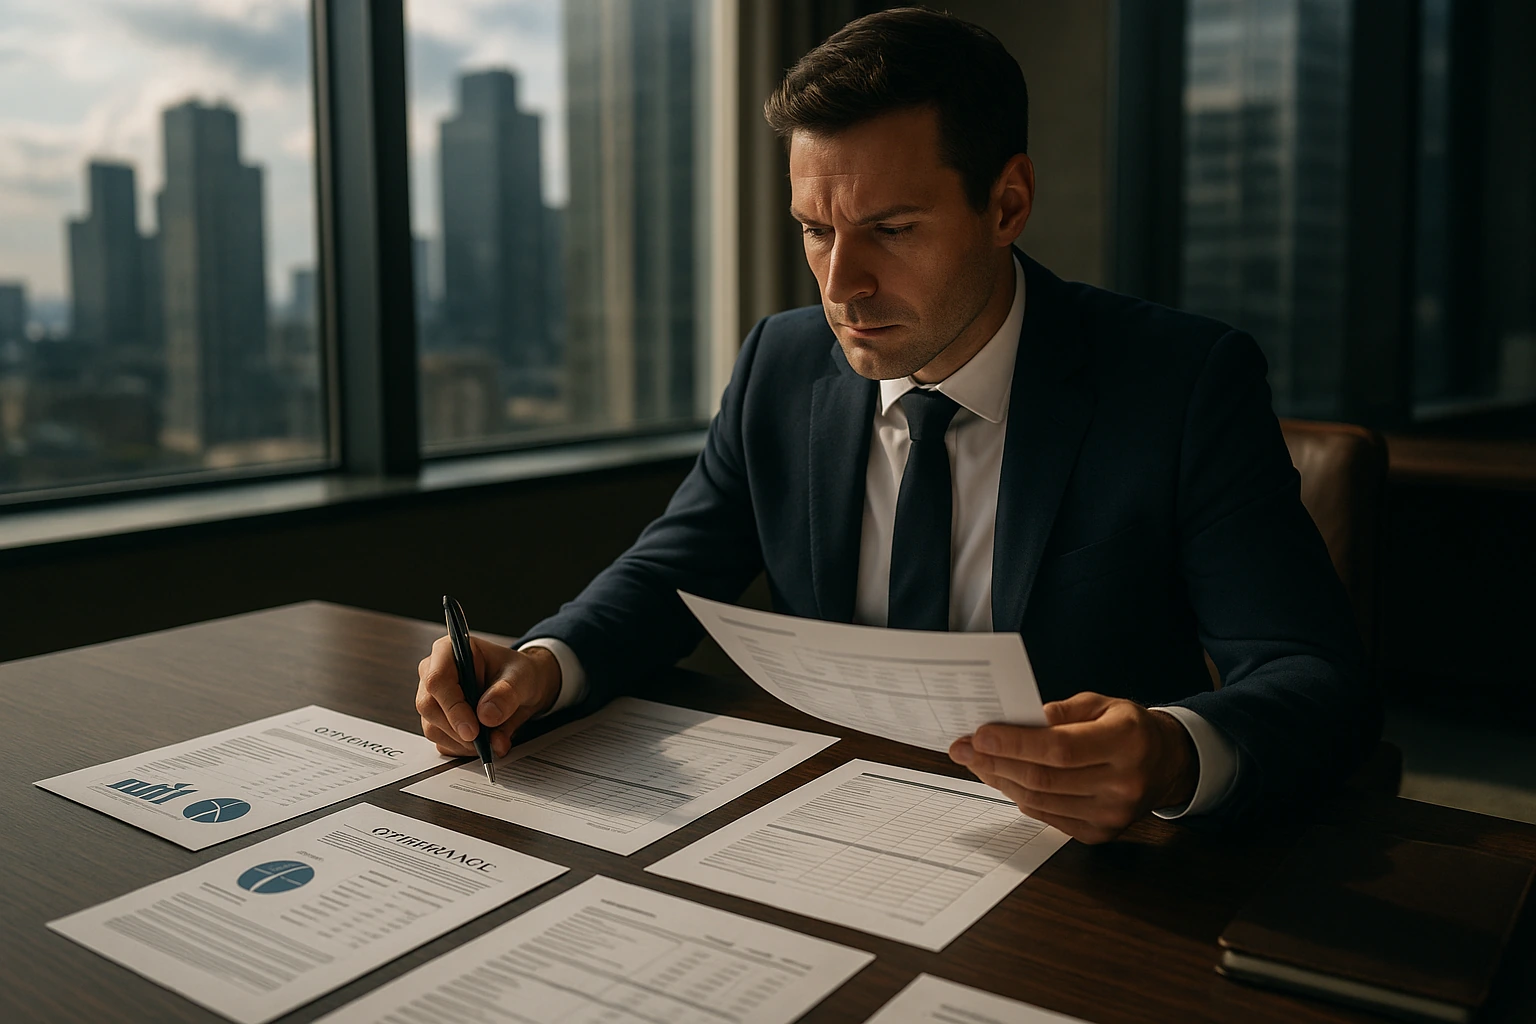
Start by building a simple spreadsheet with one column per quote. Before you look at price, fill in the same rows for every quote.
The Numbers to Match
- Per-occurrence limit: The most the policy pays for a single incident.
- General aggregate: The most it pays across all claims during the policy term.
- Products-completed operations aggregate: This limit is critical for trades because claims often arrive after the job is finished.
- Deductible or self-insured retention: The amount you pay before coverage begins, and whether it applies per claim or per policy year.
- Sublimits: Smaller caps inside the policy, such as damage to rented premises or medical payments.
Many small businesses carry a $1 million per-occurrence and $2 million aggregate general liability limit, partly because clients and general contractors often require it in their contracts. If one quote is written at $500,000 per occurrence, it is not a competing offer. It is a smaller product.
Occurrence vs. Claims-Made
Check whether each policy is written on an occurrence form or a claims-made form. An occurrence policy covers incidents that happen during the policy period, no matter when the claim is filed.
A claims-made policy covers only claims reported while the policy is active, subject to a retroactive date. This structure is standard for Errors and Omissions Insurance (E&O), so compare retroactive dates and the cost of extended reporting periods across quotes.
| Item | Quote A | Quote B | Quote C |
|---|---|---|---|
| Per occurrence / aggregate | Record | Record | Record |
| Deductible (per claim or annual) | Record | Record | Record |
| Policy form (occurrence or claims-made) | Record | Record | Record |
| Key exclusions | Record | Record | Record |
| Insurer AM Best rating | Record | Record | Record |
| Annual premium plus fees | Record | Record | Record |
Ask every carrier to re-quote at the same limits and deductible so the premium column reflects real price differences. Our guide to getting the best business insurance rate explains how to request matching quotes efficiently.
Read Exclusions and Endorsements
Exclusions are where low-priced quotes most often save money at your expense. A policy can show the right limits and still exclude the work you actually do.
Exclusions That Commonly Affect Small Businesses
- Classification limitations: Coverage applies only to the operations listed on the declarations. A carpenter classified for interior finish work may not be covered for structural framing.
- Height or depth restrictions: Some contractor policies exclude work above a specified number of stories or below grade.
- Subcontractor exclusions: Claims arising from uninsured subcontractors may be excluded entirely.
- Residential or new construction exclusions: These are common in contractor liability and can eliminate a core revenue stream.
- Professional services exclusions: Estheticians, tattoo artists, and fitness instructors should confirm whether injuries caused by their services are covered or carved out.
- Assault and battery or liquor exclusions: Bars, event venues, and dance studios should review these closely.
Endorsements Worth Comparing
Endorsements modify the base policy, either adding coverage or restricting it. Request the full forms list for each quote, not just the declarations page.
- Blanket additional insured status, which many general contractors and commercial landlords require.
- Waiver of subrogation, often required in construction contracts.
- Primary and noncontributory wording.
- Coverage for owned tools, which a separate Tools and Equipment Insurance policy or inland marine endorsement may provide.
A Business Owners Policy (BOP) bundles property and liability coverage, but bundled forms vary from one carrier to another. Compare what each BOP includes, such as business income or equipment breakdown, instead of assuming two BOPs are equivalent. One owner’s experience bundling business insurance policies shows how much the package structure can change total cost.
Check Insurer Financial Strength
A policy is only as dependable as the company backing it. Financial strength ratings measure an insurer’s ability to pay claims, including large or delayed ones.
How to Read AM Best Ratings
AM Best is an independent credit rating agency that specializes in the insurance industry. Its Financial Strength Ratings use letter grades.
- A++ and A+: Superior
- A and A-: Excellent
- B++ and B+: Good
- B and below: Fair or weaker, which deserves extra scrutiny
Many contracts and lenders require insurers rated A- or better. If a quote comes from a lower-rated carrier, confirm that your client contracts will accept it before you bind coverage.
Admitted vs. Non-Admitted Carriers
Admitted carriers are licensed by your state’s insurance department and typically participate in the state guaranty fund, which offers limited protection if the insurer becomes insolvent. Non-admitted, or surplus lines, carriers can write high-risk classes that admitted markets decline, but they generally fall outside guaranty fund protection.
Get Your Business Insurance:
Get a Quote
Surplus lines coverage is common for roofers, tattoo parlors, and liquor-serving businesses. When a non-admitted carrier is the only option, place greater weight on its financial strength rating.
Claims Reputation
Ratings measure solvency, not service. Check your state insurance department’s consumer complaint data and ask your agent how each carrier handles claims in your trade.
The practical value of a responsive carrier is clear in this $250K roofing liability claim, where proper coverage and claims handling determined whether the business survived.
Questions to Ask Your Agent
A good agent should answer these questions in writing. Vague answers usually point to coverage gaps.
- Are all quotes at identical limits, deductibles, and policy forms? If not, ask for re-quotes at matching terms.
- Which exclusions differ between these policies? Ask for the specific form numbers.
- Is my business classified correctly? Misclassification can void coverage for the work you perform most often.
- Is the premium auditable? General liability and Workers’ Comp Insurance are often rated on payroll or revenue, and an end-of-term audit can raise your final cost.
- What fees, taxes, and minimum earned premiums apply? Surplus lines policies frequently add taxes and fees, and some policies keep a minimum premium if you cancel early.
- Does the policy satisfy my contracts? Share client agreements so the agent can confirm additional insured, waiver, and limit requirements.
- Do my vehicles need commercial coverage? A personal auto policy may deny claims involving business use.
Sole operators with no employees should also ask whether they need workers’ comp to meet client or state requirements. Coverage for sole proprietor workers compensation varies by state and by trade.
Frequently Asked Questions
How many small business insurance quotes should I compare?
Compare enough quotes to establish a real market price for identical coverage, typically from several carriers.
Get Your Business Insurance:
Get a Quote
- Include both admitted and surplus lines carriers if your trade is high-risk.
- Use the same application details for every quote.
- Discard any quote that cannot match your required limits.
- See how one contractor saved by comparing quotes.
Is the cheapest quote ever the right choice?
The cheapest quote is the right choice only when its limits, exclusions, and carrier rating match the alternatives.
- Confirm the same classification codes appear on each quote.
- Check for added fees and audit exposure.
- Verify that contract requirements are met.
- Learn how to find affordable liability coverage without gaps.
What policies should a small business compare quotes for?
Most small businesses compare quotes for general liability first, then add policies based on their risks.
- Trades often need commercial auto, tools coverage, and workers’ comp.
- Service professionals may need professional liability.
- Retailers and product sellers should review product liability.
- Review the common small business policies.
Why do contractor quotes vary so much?
Contractor quotes vary because carriers price trade classification, payroll, revenue, and claims history differently.
- Roofing and structural work carry higher rates.
- Subcontractor use affects pricing and exclusions.
- Location and state rules change requirements.
- Read about typical contractor insurance cost drivers.
Should I compare commercial auto quotes separately?
Comparing commercial auto separately makes sense because its pricing depends on vehicles, drivers, and radius of operation.
- List every driver and vehicle the same way on each application.
- Match liability limits and physical damage deductibles.
- Check whether tools inside the vehicle are covered.
- Review commercial auto costs for tradespeople.
Do sole proprietors compare quotes differently?
Sole proprietors follow the same process but should focus on contract requirements and the cost of minimum premiums.
- Confirm the policy names you and your business correctly.
- Check whether monthly payment options add fees.
- Ask how your revenue estimate affects audit results.
- Compare liability options for sole proprietors.
Choosing the Policy That Actually Protects Your Business
Once every quote sits in matching rows, the best value is usually clear. Pick the policy with the right limits, the fewest exclusions affecting your work, and a carrier rated A- or better.
Before binding, request the full policy forms and compare them against your client contracts. Then calendar your renewal date at least a month early so you have time to repeat the comparison with updated payroll and revenue figures.