Painters Insurance in New York
One Ladder Slip Can Cost a New York Painter $150,000
Need
Painters Insurance ?
Get a Quote
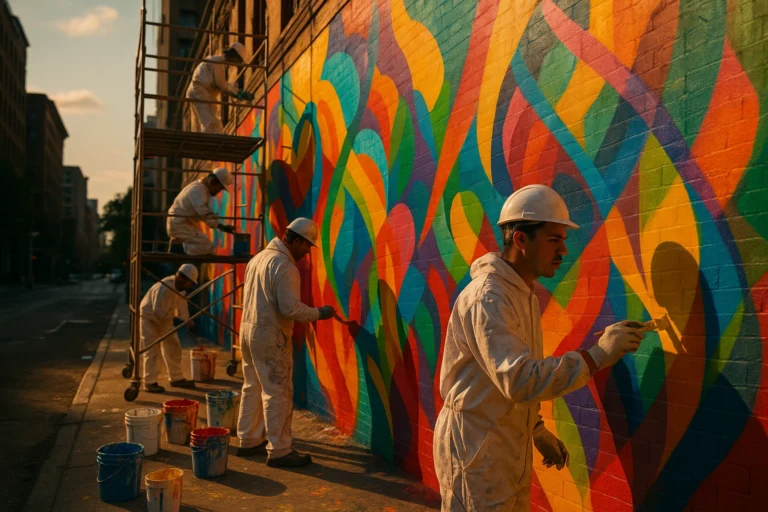
A painting contractor in Brooklyn sets up scaffolding on a three-story brownstone. A passerby walks underneath, a paint can falls, and suddenly there’s a head injury, an ambulance, and a lawsuit. Without proper insurance, that contractor is personally liable for medical bills, legal fees, and damages that can easily reach six figures.
New York is one of the most litigious states in the country, and its Labor Law (particularly Sections 240 and 241) holds contractors and property owners to strict liability standards for gravity-related injuries on job sites. That single legal detail makes painters insurance in New York fundamentally different from coverage in most other states.
Why New York’s Labor Law Changes Everything for Painters
Most articles about painters insurance treat every state the same. They shouldn’t. New York’s Labor Law Section 240, often called the “Scaffold Law,” imposes absolute liability on property owners and general contractors when a worker is injured in a fall from a height. This means even if the injured worker was partly at fault, the property owner or contractor upstream can still be held 100% responsible. For painting contractors working on ladders, scaffolding, or elevated platforms daily, this creates an enormous exposure that standard general liability policies in other states rarely account for.
What does this mean in practice? It means your insurance carrier needs to understand New York construction law. A generic policy purchased online from an out-of-state insurer may not include the endorsements or coverage limits necessary to protect you when a Section 240 claim hits. Premiums for painters in New York City tend to run higher than the national average precisely because insurers price in this legal risk. Expect to pay anywhere from $2,500 to $7,000 or more annually for general liability alone, depending on your revenue, crew size, and whether you work on residential or commercial properties.
The Core Policies Every New York Painting Contractor Needs
There is no single “painters insurance” policy. Instead, you build a coverage package from several distinct policy types. Here’s what a properly insured painting business in New York actually carries:
- General Liability Insurance: Covers third-party bodily injury and property damage. If you spill industrial solvent on a client’s hardwood floor or a pedestrian trips over your drop cloth, this policy responds. Most New York commercial clients and property managers require a minimum of $1 million per occurrence and $2 million aggregate.
- Workers’ Compensation Insurance: New York State law requires workers’ comp for virtually all employers, including painting contractors with even one employee. The New York State Workers’ Compensation Board actively audits businesses and penalties for non-compliance start at $2,000 per 10-day period. Painters are classified under relatively high-risk codes, so rates reflect the physical nature of the work.
- Commercial Auto Insurance: If you own or lease vans or trucks to haul equipment, New York requires commercial auto coverage. Minimum liability limits are $25,000/$50,000 for bodily injury, but most contractors carry significantly higher limits to avoid personal exposure in a serious accident.
- Inland Marine Insurance: Spray rigs, power washers, compressors, and specialized tools can represent $10,000 to $50,000 or more in equipment. Inland marine covers these items while in transit or stored on job sites, which general liability does not.
- Umbrella or Excess Liability: Given New York’s litigious environment, many painting contractors carry a $1 million to $5 million umbrella policy that sits on top of their general liability and auto policies. This is especially important for commercial work or any project involving scaffolding above two stories.
If you’re exploring how different policies and costs for painting contractors compare nationally, New York consistently ranks among the most expensive states for each of these coverages.
How Much Painters Insurance Actually Costs in New York City vs. Upstate
Location within New York State significantly affects premiums. A two-person painting crew operating in Manhattan will pay considerably more than a similar operation in Syracuse or Albany. Several factors drive this gap:
- Population density and foot traffic: More people near your job site means more potential third-party claims.
- Building height and type: High-rise exterior work in Midtown carries far greater risk (and premium) than interior residential repaints in suburban Westchester.
- Local court tendencies: Jury awards in New York City boroughs have historically been larger than those in upstate counties, and insurers price this in.
As a rough benchmark, a solo residential painter upstate might secure a basic general liability policy for $1,500 to $2,500 per year. That same policy for a five-person commercial crew in Brooklyn or Queens could run $5,000 to $10,000 or more annually. Workers’ comp adds substantially to these figures, often equaling or exceeding the general liability premium for painting operations.
Getting Hired: Insurance Requirements from GCs and Property Managers
Here’s something many new painting contractors learn the hard way. You can be the best painter in the five boroughs, but if your certificate of insurance doesn’t meet the general contractor’s or building manager’s requirements, you won’t get the job. Period.
Most commercial projects in New York require you to name the GC, property owner, and sometimes the building management company as “additional insureds” on your general liability policy. They also typically require a waiver of subrogation endorsement, which prevents your insurer from suing them after paying a claim on your behalf. These endorsements are standard, but not every bare-bones policy includes them automatically. Before purchasing a policy, confirm with your agent that additional insured endorsements and waivers of subrogation can be added at no or minimal cost.
Many property managers in NYC also require proof of lead paint liability coverage or pollution liability if the project involves pre-1978 buildings. Given that a significant portion of New York City’s housing stock predates 1978, this comes up frequently. A standard general liability policy typically excludes pollution-related claims, so you may need a separate environmental or pollution liability endorsement.
Get Your Business Insurance:
Get a Quote
Workers’ Comp in New York: No Exceptions for “Independent” Painters
New York takes an aggressive stance on workers’ compensation. Unlike some states that exempt sole proprietors or businesses with fewer than a certain number of employees, New York requires coverage for essentially all workers in the construction trades. If you hire even one part-time helper to tape and prep, you need a workers’ comp policy or a formal exemption certificate.
The consequences of operating without it are severe. Beyond the financial penalties from the Workers’ Compensation Board, uninsured contractors can face criminal misdemeanor charges. General contractors who hire uninsured subs also face liability, which is why most GCs verify your workers’ comp certificate before allowing you on site. If you’re a true sole proprietor with no employees, you can apply for a CE-200 exemption certificate through the state, but be certain your working arrangement genuinely qualifies.
Understanding New York small business insurance requirements broadly can help you avoid costly compliance gaps across all your coverage needs.
Reducing Your Premiums Without Cutting Corners
Higher premiums don’t mean you’re stuck overpaying. Several legitimate strategies can lower your costs while maintaining proper coverage:
- Bundle your policies. A Business Owner’s Policy (BOP) combines general liability with commercial property coverage, often at a lower combined premium than purchasing each separately.
- Maintain a clean claims history. Insurers reward contractors with few or no claims over the past three to five years. Even one large claim can spike your renewal rates by 20% to 40%.
- Invest in safety training. Documented OSHA safety training programs, proper ladder certifications, and written safety protocols can qualify you for premium discounts with certain carriers.
- Classify your work accurately. If you primarily do interior residential repaints, make sure your policy reflects that rather than a broader (and more expensive) exterior commercial classification.
- Shop through an independent agent. An independent agent who works with multiple carriers can compare quotes specific to painting contractors. Captive agents at a single company cannot do this.
Contractors in adjacent trades, like those seeking carpenters insurance in New York, face similar premium dynamics and can benefit from the same strategies.
Frequently Asked Questions
Is painters insurance legally required in New York?
General liability insurance is not technically mandated by state law for all painters, but workers’ compensation insurance is required for any painting business with employees. In practice, however, nearly every general contractor, property manager, and commercial client in New York will require proof of general liability coverage before allowing you on a project. Operating without it effectively locks you out of most professional work.
Get Your Business Insurance:
Get a Quote
How much does general liability insurance cost for painters in NYC?
Costs vary based on revenue, crew size, and the type of work you perform. A solo interior residential painter might pay $1,500 to $3,000 per year, while a mid-sized commercial crew working on exteriors in the five boroughs could pay $5,000 to $10,000 or more. Projects involving scaffolding or heights push premiums higher due to the liability exposure under New York’s Scaffold Law.
Do I need lead paint coverage as a painter in New York?
If you work on buildings constructed before 1978, which includes a large portion of New York City’s housing stock, you face potential exposure to lead-based paint. Standard general liability policies typically exclude pollution-related claims, and lead paint disturbance falls under that exclusion. A pollution liability endorsement or separate environmental liability policy is strongly recommended for any painter working in older buildings.
Can I get a workers’ comp exemption as a sole proprietor painter in New York?
Yes, sole proprietors with no employees can apply for a CE-200 certificate of attestation of exemption through the New York State Workers’ Compensation Board. This certificate proves to clients and GCs that you are legally exempt. However, the moment you hire any worker, even a temporary helper, you must obtain a workers’ comp policy immediately.
What is an additional insured endorsement and why do GCs require it?
An additional insured endorsement extends your general liability coverage to include another party, typically the general contractor or property owner, for claims arising from your work. GCs require this because it gives them a layer of protection under your policy if a claim originates from your painting operations. Most standard commercial general liability policies allow you to add additional insureds, but confirm this with your agent before binding coverage.
Does my painters insurance cover damage to a client’s property?
Yes, general liability insurance typically covers property damage caused by your operations. If you accidentally splatter paint on a client’s furniture, damage a fixture while moving equipment, or stain flooring with solvent, your policy should respond after you meet the deductible. However, damage to your own work (such as having to redo a poor paint job) is generally not covered. That falls under your cost of doing business.
Protect Your Business Before the Next Job Starts
Painting in New York is physically demanding work with real financial risk attached to every project. The combination of the state’s strict labor laws, high litigation rates, and demanding commercial clients means that proper insurance isn’t optional. It’s the cost of doing business professionally. Start by getting quotes from at least three carriers through an independent agent who specializes in contractor insurance. Make sure your policy addresses New York’s unique legal requirements, especially around scaffold liability and workers’ compensation. The time to sort out your coverage is before you set foot on the next job site, not after a claim forces you to figure it out under pressure.
Near Me: More insurance info for small businesses in your state:
 Insurance for dog walkers in New York (NYC)
 Roofing insurance in New York (NYC)
 Handyman Liability Insurance in New York – NYC
 New York General Liability Insurance – NYC
 New York Small Business Insurance (NYC) – policies and cost
 New York Commercial Auto Insurance – NYC
 New York Retail Store Insurance (NYC) – policies and cost
 Carpenters Insurance in New York
 New York Esthetician Insurance
 General Contractor Insurance in New York: What You Need to Know