Valet Trash Business Insurance
Valet Trash Business Insurance: What You Need and What It Costs
Valet trash business insurance typically includes general liability, commercial auto, and workers’ compensation coverage, with annual premiums ranging from $2,000 to $8,000 depending on company size, number of employees, and service area.
Need
Valet Trash Business Insurance ?
Get a Quote
A single slip-and-fall claim from a resident at an apartment complex can cost more than your entire annual premium.
Most property managers now require proof of insurance before signing a service contract, making coverage not just smart but mandatory for winning bids.
This guide breaks down every policy type you need, explains what each one protects, and shows you how to keep costs under control without leaving gaps in your coverage.
If you’re running a doorstep collection service or planning to start a valet trash operation, understanding your insurance requirements is the first real business decision you’ll make.
Why Valet Trash Business Insurance Is Non-Negotiable
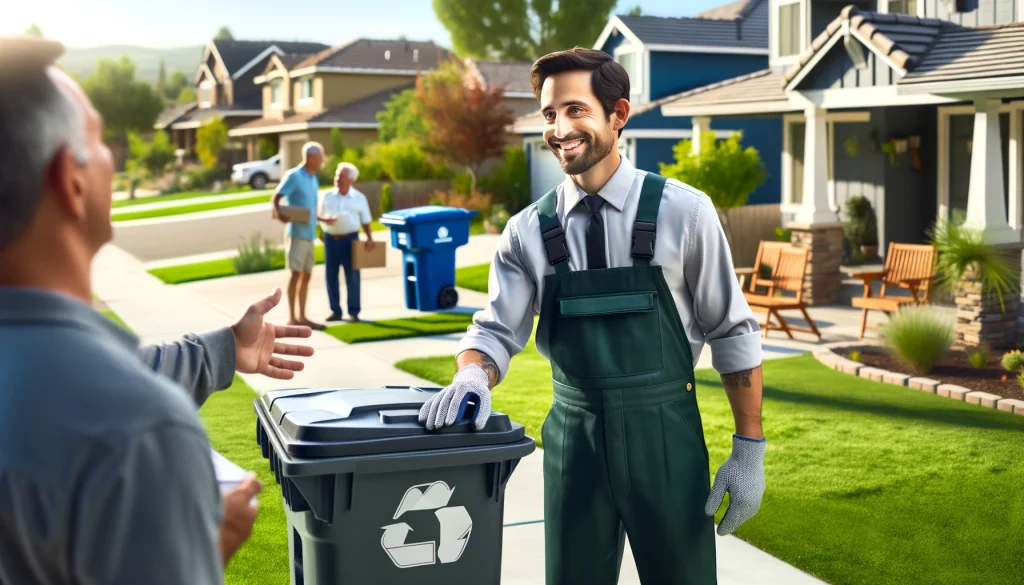
Picture this: one of your collectors accidentally dents a resident’s car door while wheeling bins through a parking garage at 9 p.m.
The repair bill hits $3,400.
Without insurance, that comes straight from your operating budget.
Valet trash businesses face a unique combination of risks that most service companies don’t encounter together: nighttime work, proximity to personal vehicles, access to private doorsteps, and repeated physical labor across slippery or poorly lit walkways.
Property management companies understand these risks, which is why nearly all of them require a certificate of insurance (COI) listing them as an additional insured before they’ll award a contract.
Losing a contract because you lack proper coverage is a preventable failure.
Beyond contract requirements, your state likely mandates certain coverages once you hire employees.
Most states require Workers’ Comp Insurance as soon as you bring on your first W-2 worker, and valet trash collectors face above-average injury rates due to repetitive lifting, weather exposure, and nighttime visibility hazards.
Insurance isn’t overhead; it’s the cost of staying operational.
One uninsured incident can wipe out months of revenue and permanently damage your reputation with property managers who talk to each other.
Get Your Business Insurance:
Get a Quote
Core Policies Every Valet Trash Company Needs
General Liability Coverage
General Liability Insurance is the foundation of your coverage stack.
It protects against third-party bodily injury claims, property damage, and advertising injury.
When a resident trips over a bin your team left in a walkway, or a collector scratches a hallway wall with a cart, general liability responds.
Most apartment communities require a minimum of $1,000,000 per occurrence and $2,000,000 aggregate.
Commercial Auto Insurance
Your crew drives between apartment communities every night.
Get Your Business Insurance:
Get a Quote
Personal auto policies exclude business use, meaning any accident during a route leaves you fully exposed.
Commercial auto covers your vehicles (owned, leased, or hired) for collisions, liability, and sometimes cargo damage.
If employees use personal vehicles, you’ll also need hired and non-owned auto coverage to fill that gap.
Workers’ Compensation
Collectors lift heavy bags, navigate stairs in the dark, and work in rain, ice, and extreme heat.
Back injuries, slips, and repetitive strain claims are common in this line of work.
Workers’ comp covers medical expenses and lost wages for injured employees while protecting you from personal injury lawsuits filed by your own team.
Umbrella or Excess Liability
An umbrella policy kicks in when a claim exceeds your underlying policy limits.
For a valet trash company servicing 15 or more communities, a $1,000,000 umbrella policy typically costs between $400 and $800 per year and can prevent a catastrophic out-of-pocket loss.
Additional Coverage Options for Valet Trash Operations
Equipment and Tools Coverage
Carts, bins, branded containers, GPS devices, and hand trucks represent a real investment.
Tools and Equipment Insurance covers theft, vandalism, and accidental damage to these items whether they’re stored at your facility or deployed across apartment properties.
Replacement costs add up fast when you’re outfitting crews for 20-plus communities.
Errors and Omissions Protection
What happens when you miss a scheduled pickup for an entire building, and the property manager loses a resident over the complaint?
Errors and Omissions Insurance (E&O) covers claims arising from professional mistakes, missed services, or failures to perform according to your contract terms.
It’s particularly relevant if your contracts include service level agreements with financial penalties.
Business Owners Policy
A Business Owners Policy (BOP) bundles general liability with commercial property coverage into a single, often discounted package.
For smaller valet trash operators with an office, storage space, or warehouse, a BOP can save 10 to 15 percent compared to purchasing those policies separately.
Understanding the differences between a BOP and standalone general liability helps you decide which structure makes more financial sense at your current scale.
How to Reduce Your Valet Trash Business Insurance Costs
Premium costs aren’t fixed, and you have more control over them than most operators realize.
Here are proven strategies to lower your rates without cutting essential coverage:
- Implement formal safety training. Insurers offer lower rates to companies with documented training programs covering proper lifting techniques, nighttime visibility protocols, and vehicle safety.
- Maintain a clean claims history. Every claim you file raises your experience modification rate. Handling minor incidents (under $500) internally, when appropriate, keeps your loss ratio low.
- Bundle policies with one carrier. Purchasing general liability, commercial auto, and workers’ comp from the same insurer often triggers multi-policy discounts of 5 to 15 percent.
- Raise your deductibles strategically. Moving from a $500 to a $1,000 deductible on general liability can reduce premiums by 10 percent or more, provided you have cash reserves to cover smaller claims.
- Classify employees correctly. Workers’ comp rates vary by job classification code. Making sure collectors, drivers, and office staff are coded separately prevents you from paying collector-level rates on administrative employees.
Reviewing your policies annually matters more than most owners think.
As your company grows, your risk profile changes, and last year’s coverage may leave new gaps or include unnecessary line items.
Use a valet trash calculator to project revenue against insurance costs and make sure your margins stay healthy as you scale.
Valet Trash Business Insurance: What Property Managers Expect
Winning contracts in this industry depends heavily on your ability to meet insurance specifications.
Property managers at institutional apartment REITs and third-party management firms typically require specific minimums before they’ll sign a vendor agreement.
Here’s what most contracts demand:
- General liability: $1,000,000 per occurrence, $2,000,000 aggregate
- Commercial auto: $1,000,000 combined single limit
- Workers’ compensation: statutory limits per your state
- Umbrella: $1,000,000 (often required for portfolios of 10+ communities)
- Additional insured endorsement naming the property management company and ownership entity
Failing to meet even one of these requirements can disqualify your bid entirely.
Some management companies also request a waiver of subrogation, which prevents your insurer from suing the property owner to recover claim payments.
This endorsement typically adds a small cost to your policy but is standard in the waste management service sector.
Keep digital copies of all certificates and endorsements organized by property, and set calendar reminders 30 days before each policy renewal so you never have a lapse in coverage.
A coverage gap, even for a single day, can trigger a contract default clause.
If you’re still in the planning stages, our guide on how to start a business covers the foundational steps that come before your first insurance application.
Frequently Asked Questions
How much does valet trash business insurance cost per year?
Annual premiums typically range from $2,000 to $8,000 for a small to mid-sized operation.
The exact cost depends on your number of employees, annual revenue, claims history, and the states where you operate.
Companies with fewer than five employees and clean loss records usually land on the lower end of that range.
Do I need insurance if I’m a solo operator with no employees?
Yes, you still need general liability and commercial auto at minimum.
Property managers require a certificate of insurance regardless of your company size.
Without coverage, you won’t be able to sign service agreements with apartment communities, which means no revenue.
Even sole proprietors face personal asset exposure from third-party injury or property damage claims.
What type of insurance do apartment complexes require from valet trash vendors?
Most apartment communities require general liability ($1M/$2M), commercial auto ($1M), and workers’ compensation at statutory limits.
They also typically require an additional insured endorsement naming the property owner and management company on your policy.
Larger portfolios may add umbrella liability and waiver of subrogation requirements.
Does general liability cover damage to residents’ vehicles?
Yes, general liability typically covers third-party property damage, including damage to vehicles caused by your operations.
If a collector’s cart rolls into a parked car and causes a dent, your general liability policy would respond to that claim.
However, damage caused while driving a company vehicle falls under your commercial auto policy instead.
Can I get valet trash business insurance if I just started my company?
Absolutely.
Many commercial insurers write policies for new businesses, though you may pay slightly higher rates in your first year due to the lack of operating history.
Providing a detailed business plan, safety protocols, and proof of industry training can help lower your initial premiums.
Some insurers specialize in service-based startups and offer flexible payment plans.
Is a Business Owners Policy better than buying separate policies?
For smaller operations with office or storage space, a BOP often provides better value because it bundles general liability and commercial property coverage at a discounted rate.
However, a BOP doesn’t include commercial auto or workers’ comp, so you’ll still need those as standalone policies.
Compare total costs for both approaches with your insurance agent before committing.
Conclusion
Valet trash business insurance isn’t a checkbox on a to-do list.
It’s the structural foundation that lets you sign contracts, protect your crew, and survive the inevitable claim that every service business eventually faces.
Start with general liability, commercial auto, and workers’ comp as your non-negotiable base.
Add E&O, equipment coverage, and an umbrella policy as your contract volume grows.
Bundle where it makes sense, train your team consistently, and review your coverage every year as your operation scales.
The operators who treat insurance as a strategic advantage, not just an expense, are the ones who win larger contracts and build lasting relationships with property managers.
Get quotes from at least three carriers, compare not just premiums but coverage terms, and make sure every policy meets the minimum requirements your target clients demand.
Your next contract depends on it.