Mobile Car Detailing Insurance
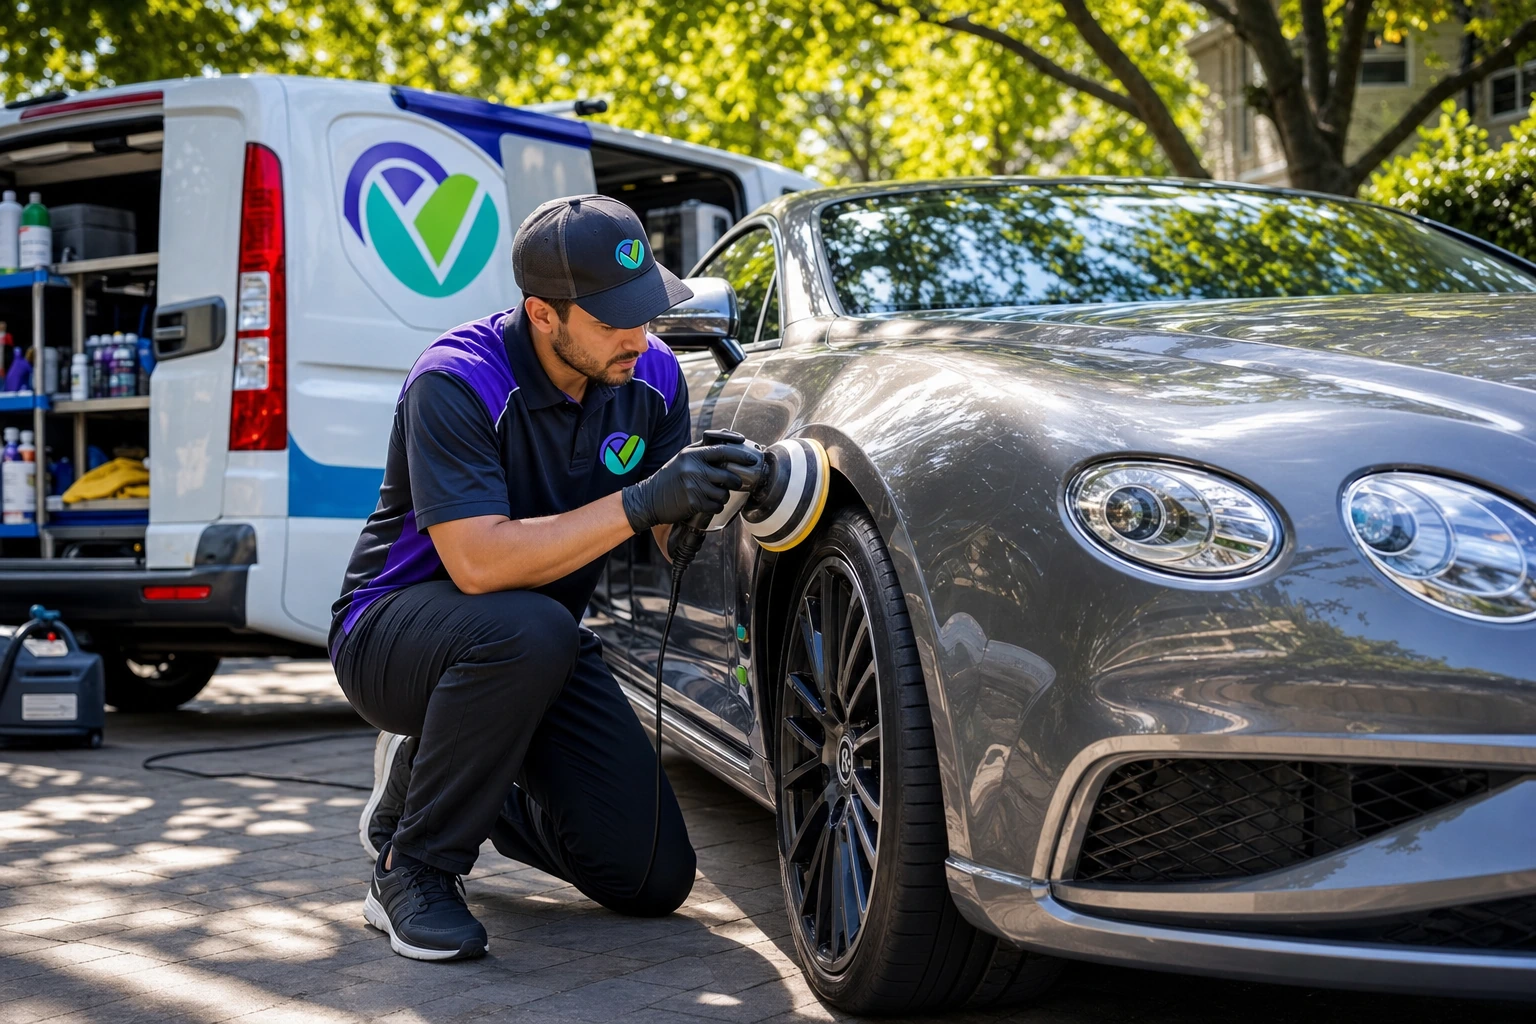
One swirl mark from a worn buffing pad or one chemical stain on a client’s driveway can cost more than a month of detailing income. Mobile car detailing insurance is a bundle of business policies, usually general liability, garagekeepers coverage, commercial auto, tools and equipment coverage, and workers’ compensation if you have employees. Together, these policies pay for customer injuries, damage to client vehicles and property, accidents on the road, and stolen gear.
Need
Mobile Car Detailing Insurance ?
Get a Quote
Car wash owners need many of the same policies. Because they also own or lease a building, tunnel equipment, and a lot full of customer cars, car wash owners also need property coverage and higher liability limits.
Costs depend on your services, payroll, vehicles, and claims history. The estimated cost ranges below give you a realistic starting point before you request quotes.
What risks do mobile detailing and car wash businesses face?
Every service you offer creates a specific kind of exposure. Paint correction carries more risk than a basic hand wash, and steam cleaning a leather interior carries different risks than vacuuming carpets. The table below matches common services to the claims they most often lead to.
| Service category | Typical work | Main insurance risk |
|---|---|---|
| Exterior detailing | Hand washing, waxing, polishing, paint correction, sealants and ceramic coatings | Scratches, burned or hazed paint, trim damage on the client’s vehicle |
| Interior detailing | Vacuuming, steam cleaning, upholstery stain removal, leather conditioning, odor elimination | Discolored leather, water-damaged electronics, chemical residue complaints |
| Additional services | Engine detailing | Water or degreaser reaching electrical components |
| Automated or tunnel car wash | Conveyor washes, brushes, dryers, vacuum stations | Damaged mirrors and antennas, customer slip-and-fall injuries |
Beyond the work itself, detailers and car wash operators face several business risks:
- Theft or loss of tools and equipment, such as pressure washers, extractors, and polishers left in a van overnight
- Auto accidents while driving to job sites
- Injuries to employees from slips, falls, and chemical exposure
- Business interruption caused by weather, equipment failure, or illness
- Damage to a client’s home or business property, such as a chemical spill staining a customer’s driveway
The first category in the table, damage to the customer’s own vehicle, is the risk most new detailers underestimate. It is also the risk a standard liability policy often does not cover, so it gets its own section below. If you are still planning your operation, our guide on starting a mobile detailing business covers licensing and setup alongside insurance.
Which policies make up mobile car detailing insurance?
No single policy covers everything. Most detailers build coverage from the policies below, and car wash owners usually add property coverage on top.
Garagekeepers insurance
General liability policies usually exclude damage to property in your “care, custody or control.” A customer’s car that you are polishing falls under that exclusion. Garagekeepers insurance fills the gap and pays for damage to customer vehicles while you work on them or hold them. Ask whether a policy is “legal liability” (pays only when you are at fault) or “direct” (pays regardless of fault). Also confirm with the insurer that the policy applies to mobile work done at a client’s location.
General liability
General liability coverage handles third-party bodily injury and property damage. Examples include a client slipping on your soapy runoff or degreaser staining their driveway. Most commercial clients and fleet contracts require proof of this coverage.
Commercial auto
Personal auto policies often exclude vehicles used mainly for business. A commercial auto policy covers your van or truck, including mounted water tanks in some cases. If employees drive their own cars to jobs, ask about non-owned auto liability.
Tools and equipment (inland marine)
This coverage protects portable gear wherever it is: in the van, at a job, or in storage. Equipment insurance matters most to mobile detailers, since their entire business travels with them.
Workers’ compensation
Workers’ comp pays medical bills and lost wages when employees are hurt on the job. Most states require it once you hire. For details, see our overview of workers’ comp for small businesses.
Business owners policy, property, E&O and cyber
A business owners policy (BOP) bundles general liability with property coverage, often at a lower combined price. A car wash or a detailer with a shop or storage location may need commercial property insurance for the building and its equipment. Errors and omissions insurance covers financial losses from professional advice or service failures, such as a missed fleet-contract deadline. It does not pay for physical damage to a vehicle’s paint. If you take online bookings and card payments, cyber insurance for small businesses covers data breach costs.
How much does auto detailing and car wash insurance cost?
The figures below are rough annual estimates for small operations. Your actual price depends on your state, limits, deductibles, payroll, revenue, and claims history. Use these ranges to judge whether a quote is reasonable, not as a price promise.
| Policy | Estimated annual cost: solo mobile detailer | Estimated annual cost: car wash location |
|---|---|---|
| General liability | $400-$1,200 | $1,500-$6,000+ |
| Garagekeepers | $300-$1,500 | $1,000-$5,000+ |
| Commercial auto (per vehicle) | $1,500-$4,000 | Varies by fleet |
| Tools and equipment | $150-$700 | Often included in property |
| Workers’ compensation | Not required for most solo owners | Based on payroll and state rates |
| BOP / commercial property | $500-$2,000 | $3,000-$15,000+ |
| Cyber | $400-$1,500 | $500-$2,500 |
A car wash costs more to insure because it has a fixed property, heavy machinery, a steady flow of customers walking on wet surfaces, and many vehicles passing through each day. A mobile detailer’s largest single cost is usually commercial auto.
Get Your Business Insurance:
Get a Quote
What raises or lowers your premium
- High-value services such as paint correction and ceramic coatings, which can raise garagekeepers costs
- Working on luxury or exotic vehicles, which raises the per-vehicle limit you need
- Your driving record and the number of vehicles on the policy
- Payroll size and job classification, which set workers’ comp rates
- Prior claims, location, and higher limits demanded by commercial contracts
You can lower costs by bundling policies, choosing a higher deductible, and keeping documented safety procedures. The U.S. Small Business Administration’s insurance guide explains which coverages are legally required and which are optional. To estimate vehicle costs for your budget, try the business auto expense calculator.
How do you choose coverage for your type of detailing business?
The right mix depends on how you operate. Here is how coverage typically differs across three common setups.
Solo mobile detailer
Start with general liability, garagekeepers, commercial auto, and tools coverage. If you work out of a personal truck, tell your auto insurer about the business use. An undisclosed business use can lead to a denied claim.
Mobile detailing crew with employees
Add workers’ compensation and non-owned auto liability. Raise your garagekeepers limit to match the most expensive car your crew might handle in one day. State rules also differ. Owners in some states should read our guides to auto detailing insurance in California and starting a detailing business in Texas.
Fixed car wash or detail shop
Add commercial property or a BOP, plus higher liability limits. Consider equipment breakdown and business interruption coverage, so a failed conveyor or a storm closure does not drain your cash reserves.
Steps to get quotes
- List your services, vehicles, employees, equipment value, and annual revenue.
- Check what limits your commercial clients or landlord require in their contracts.
- Request quotes from at least three insurers that write auto service businesses.
- Compare exclusions, especially for garagekeepers and for any work done at client locations.
- Keep certificates of insurance ready for clients who ask for proof.
Our guide on buying business insurance online walks through comparing quotes. If you are testing the business at car shows or weekend events, short-term business insurance can cover single events or trial periods.
Get Your Business Insurance:
Get a Quote
Frequently Asked Questions
Do I need insurance for a mobile auto detailing business?
Yes, because one damaged vehicle or injured client can cost more than years of premiums.
- Many commercial clients and dealerships require proof of general liability.
- Garagekeepers coverage protects the cars you work on.
- Commercial auto covers your work vehicle on the road; see commercial vehicle coverage.
Does general liability cover damage to a customer’s car?
Usually not, because customer vehicles in your care, custody or control are typically excluded.
- Garagekeepers insurance is designed for this specific gap.
- Read the exclusions section of any quote carefully.
- Learn what liability does cover in our general liability guide.
How much does auto detailing insurance cost?
A solo detailer can expect a rough estimated total of a few thousand dollars per year, with commercial auto as the largest share.
- Expect garagekeepers costs to rise for ceramic coating and exotic vehicle work.
- Bundling policies often lowers your total premium.
- A BOP bundle can combine liability and property coverage.
How much does car wash insurance cost?
Car wash insurance generally costs more than mobile detailing insurance because of property, machinery, and customer foot traffic.
- Property values drive most of the premium.
- Higher liability limits are common for busy locations.
- Related operations compare in our truck wash insurance costs guide.
Does E&O insurance cover paint damage?
No, errors and omissions insurance covers financial losses from professional mistakes, not physical damage to vehicles.
- Use garagekeepers coverage for paint and interior damage.
- E&O may help if a client sues over lost money from a missed service commitment.
- See how it works in our E&O insurance overview.
Building the Right Insurance Plan for Your Detailing Business
Mobile detailers and car wash owners face many of the same risks: damaged customer vehicles, injured clients, accidents on the road, and stolen equipment. The policy that most often gets overlooked is garagekeepers, because general liability usually excludes vehicles in your care.
Mobile operators should prioritize commercial auto and tools coverage, since the entire business travels in one vehicle. Car wash owners should prioritize property coverage and higher liability limits for a busy, wet location. Workers’ compensation becomes a requirement in most states as soon as you hire your first employee.
Your next step is to write down your services, vehicles, equipment value, and payroll. Then request at least three quotes and compare each policy’s exclusions, not only the premium. A slightly cheaper policy that excludes mobile work at client locations can leave you paying for a damaged car out of your own pocket.